So Why Are Hutterite Colonies Able to Split Their Income But Private Business Owners Have TOSI? Mismatched Socks Tax Policy
Kim G C Moody examines Canada's mismatched income-splitting rules, why leaders' actions must match their words, and the real cost of public debt.
Last week, a young relative showed up at a family gathering in flip-flops with one white sock and one black. When I pointed it out, she shrugged – she’d been rushing and hadn’t noticed. I was the first person all day to say anything.
Forty years ago, a kid in my high school class did the same thing on purpose. Everyone thought he was strange. Today, nobody bats an eye until someone who still notices points it out.
The Income Tax Act has many pairs of mismatched socks. Legislators are often more comfortable with a provision’s politics than with how it clashes with the rest of the Act, or with the “unintended consequences” that follow.
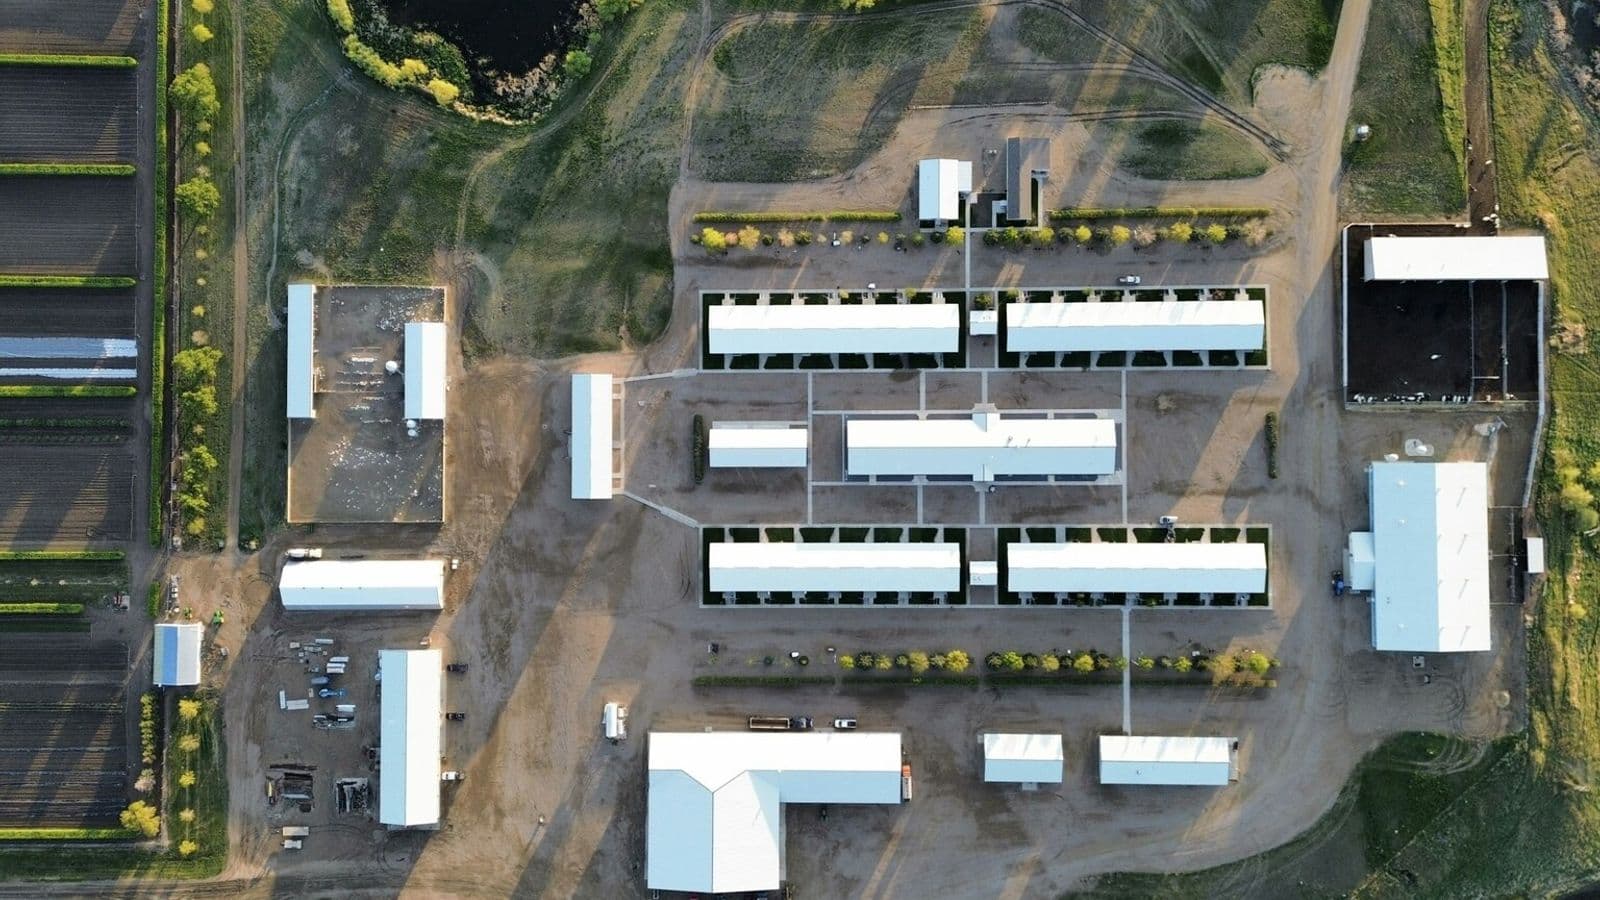
One example that has bothered me since 2017 is section 143 – the so-called Hutterite rule. If a religious congregation – as the Act defines it – runs a business communally, like a Hutterite colony’s farm, the Act deems a trust to exist. Broadly speaking, the trust can elect to split income each year among adult members by formula: one per family gets a full share, others a half share. No one has to prove hours worked or capital contributed.
This wasn’t an accident. It traces to Wipf v. The Queen in 1975: the Court found that a Hutterite colony wasn’t a commercial enterprise generating individual profits – no personal property interest, income shared by need. Parliament wrote that into section 143 in 1977, aiming to tax colonies “in the same manner as their non-Hutterian neighbours” – favourably, but not more favourably. The Federal Court of Appeal reaffirmed it in 1979. Call this the “white sock”.
Now the other foot. On July 18, 2017, then-Finance Minister Bill Morneau unveiled a package aimed at private businesses, framed as closing loopholes for wealthy Canadians trying to avoid higher tax rates, singling out income sprinkling among family members.
That was the pitch: measures that targeted high-income business owners gaming the system. What followed, after significant backlash, was sweeping amendments to the “tax on split income” (“TOSI”) rules – applying to various private interests, any income level, any family. Professional groups warned the real target would be middle-class owners, not the wealthy Morneau pitched.
Take a hypothetical Ontario couple who each own half the economic value of BakeryCo, a business they started together. Mom drives the company and owns all of the voting shares; dad stays home raising their two young kids and isn’t active in it – he owns all of the non-voting shares. Ignoring government benefits, BakeryCo is their only family income.
Say BakeryCo earns $100,000 in profits. At the small business rate, combined federal and Ontario corporate tax takes roughly $12,000, leaving about $88,000 to pay out as dividends, split evenly at $44,000 each. If TOSI didn’t apply, and that $44,000 were his only income, his tax bill – after the basic personal amount and dividend tax credit – would land around $1,100. With TOSI, the benefit of those ordinary graduated rates and personal credits disappears, and the dividend is effectively taxed at the top rate: roughly $21,000 – about nineteen times higher, purely because of who he married and what he didn’t do at the bakery that year.